Midday Softness Across Cotton Contracts
Cotton futures traded lower across virtually all contract months during Monday's session, shedding between 40 and 52 points per contract. The broad-based decline reflected a mix of cross-market headwinds and positioning shifts rather than a single commodity-specific catalyst.
Oil and Dollar Dynamics Adding Pressure
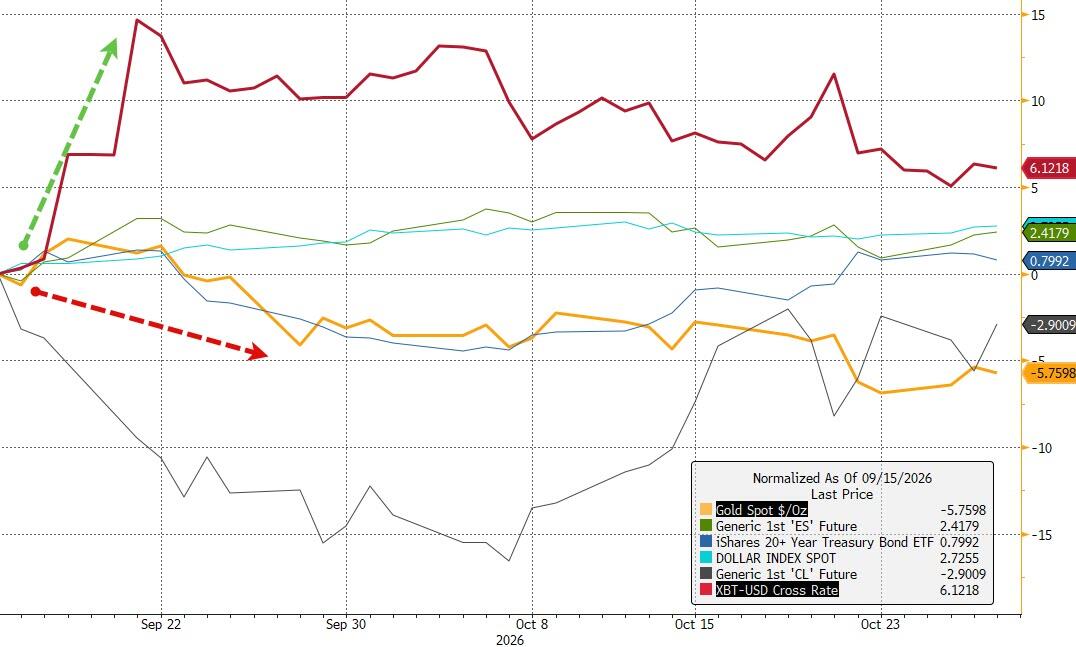
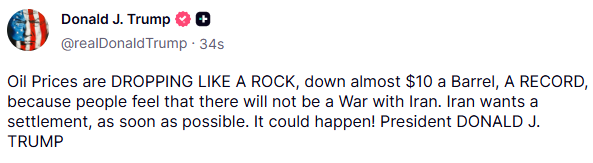
The cotton complex was not acting in isolation. Crude oil prices fell $8.20 per barrel during the same trading window, injecting a spillover drag on agricultural softs that are often correlated with energy sentiment. At the same time, the U.S. Dollar Index registered a $0.210 decline, a move that, while modest, influenced the relative competitiveness of dollar-denominated cotton on the global buying side.
Speculator Positioning Shifts
A notable factor behind the intraday weakness was the action of large managed-money speculators in the cotton market. According to positioning data, these institutional traders reduced their net exposure in cotton futures and options by 10,276 contracts. That scale of unwinding signals a deliberate de-risking by the largest discretionary and systematic players, and it typically amplifies price moves in the direction of the trade being closed.
What Traders Should Watch
For participants in the softs complex, the confluence of a steep oil decline and a visible speculator exit creates a near-term overhang on cotton pricing. The 40-to-52-point range across contracts suggests the selling was not confined to a single delivery month but spread through the curve, hinting at a broader sentiment reset rather than an isolated roll effect. Traders monitoring the complex will likely focus on whether the managed-money reduction continues into the next reporting cycle and whether the oil-driven pressure persists, as either development could extend the current weakness or, conversely, trigger a bounce if positioning becomes sufficiently stretched to the downside.