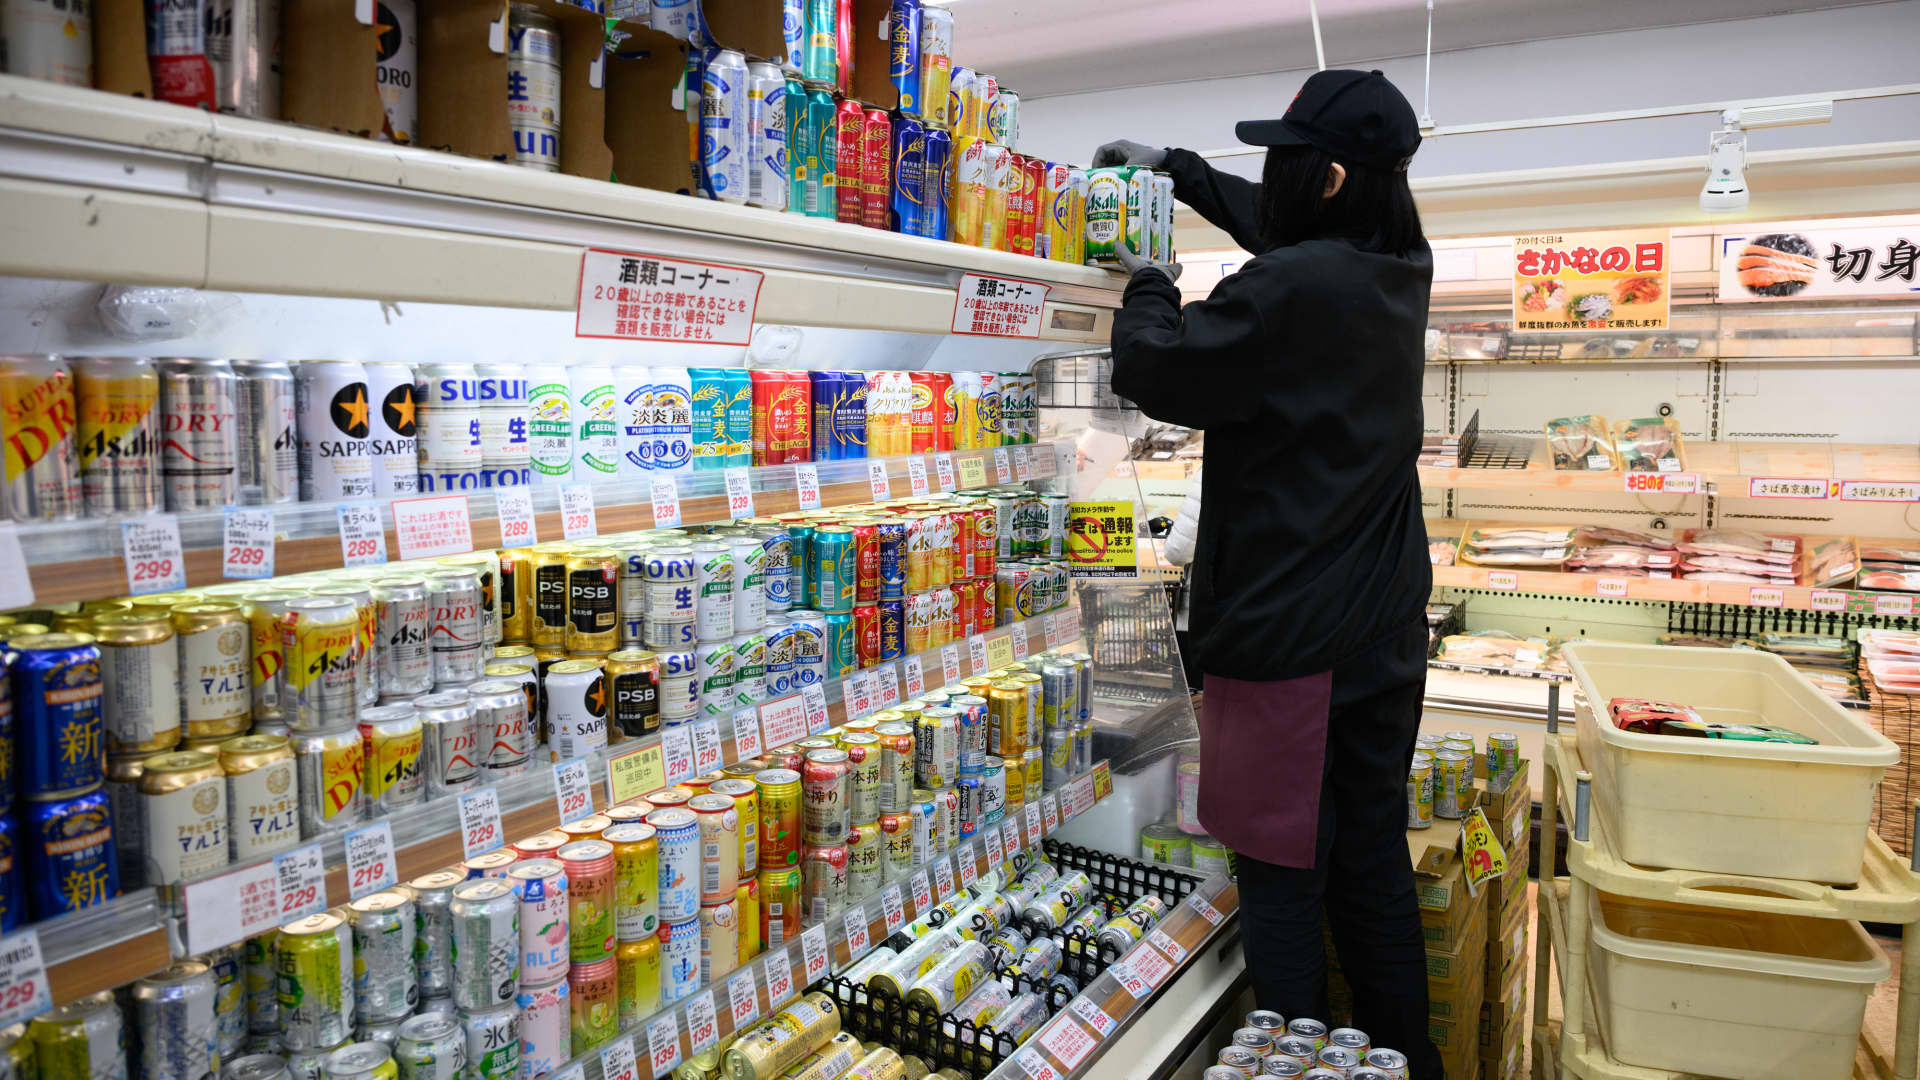
September Inflation Data Beats Expectations
Japan's core inflation rate surged to 2.1% year on year in September, marking the highest reading of the year and exceeding the 1.7% recorded the previous month. The figure, which excludes volatile fresh food prices, aligned with the consensus forecast gathered by Reuters from polled economists, though the magnitude of the acceleration caught some observers off guard.
Headline inflation also registered at 2.1% for the month. More notably, the "core-core" measure — the gauge favored by the Bank of Japan, which strips out both fresh food and energy from the basket — climbed to 2.4%, firming the case that underlying price pressures remain well above the central bank's 2% objective.
What Is Driving Price Growth
Capital Economics senior APAC economist Abhijit Surya highlighted that the speed of the acceleration was remarkable, particularly given that fresh food prices had decelerated sharply and energy prices were still in deflationary territory. Rice, a staple that had been a major inflation contributor, fell 20.6% year on year in September. Yet that decline was not enough to offset broader gains: overall goods inflation ticked up to 2.8% from 2.6% in August.
Surya pointed to the continued pass-through of the energy shock into wider pricing, noting that inflation in "other industrial products" hit a 13-month high of 3.9%. Government data indicated that durable goods and public utility charges were key contributors to the uptick. Services inflation also edged higher, rising from 1.2% to 1.5%.
Consumer energy prices actually dropped 0.6% in September and have trended lower across most of 2025, a result attributed to subsidies rolled out by the Takaichi administration that have cushioned households from the full impact of the Iran-related supply disruption.
Implications for the Bank of Japan
With underlying inflation now comfortably above the BOJ's 2% target, market participants are weighing the likelihood of additional monetary tightening. Japan hiked its policy rate by 25 basis points in September, lifting it to 1.25% — a three-decade high — as part of a gradual normalization following years of ultra-loose, reflation-oriented policy.
Surya argued that the current data set places the case for further rate increases on solid footing and projected that the BOJ would deliver another hike as early as December. The combination of a still-elevated core-core rate, persistent goods inflation, and wage-linked price dynamics all point in the direction of continued tightening.
Government Policy and Market Reaction
Finance Minister Satsuki Katayama told parliament on Wednesday that Japan was approaching a phase of sustained, wage-driven inflation, while acknowledging that elevated import costs — particularly oil purchased from costlier U.S. suppliers after Japan shifted away from Middle Eastern sources amid the Iranian conflict — were also feeding into price growth. The weak yen compounded the problem by raising the local-currency cost of energy imports.
When pressed by a lawmaker on whether the government's planned tax cuts could undermine the BOJ's disinflationary efforts, Katayama responded, as reported by Reuters, that she saw no conflict between the government's stance and the central bank's approach.
On Tuesday, Japan's Lower House opened deliberations on a bill that would slash the consumption tax on food from 8% to 1% for a two-year period, alongside income-based support payments for workers, according to public broadcaster NHK.
In markets, the Nikkei 225 index shed 1.62% on Friday, while the yen firmed to 156.15 per dollar, reflecting a modest rebalancing of risk appetite following the inflation print.